Farmers in South Africa who want a bank loan, blended finance, a retail supply contract or government support are being told that their paperwork now matters as much as their harvest. In a guide published by Food for Mzansi, a commercial sunflower farmer and an agricultural finance consultant set out what lenders look for, alongside the tax rules the South African Revenue Service (SARS) applies to farming.
"Compliance is not really red tape," said Sibo Molo of Molo Consulting. "It is a document that unlocks your Land Bank finance, blended funds, retail supply contracts and government support." He advises farmers to keep their books monthly rather than rebuilding a year of figures when a tax return or funding application is due.
Happy Letsitsa, who grows sunflowers commercially, says a farmer approaching a commercial lender should ideally have annual financial statements for the past three years, prepared by a qualified bookkeeper or accountant. The farm should also have its own bank account, so that household spending does not blur the true performance of the business.
The advice extends to an up-to-date asset register covering tractors, vehicles, machinery, equipment and livestock, with serial or vehicle identification numbers, purchase dates and values, and regular livestock counts. Such a register supports financial statements, insurance and loan applications where assets form part of the lender's assessment.
On tax, Molo notes that the Income Tax Act has an entire schedule written for farming. A registered farming vendor may, with the required SARS authorisation and a valid tax invoice, buy certain inputs such as animal feed, animal remedies, fertiliser, pesticides, plants and seeds at a zero VAT rate. Farming enterprises with a farming turnover of no more than R1.5 million over 12 months can use a six-monthly VAT period. Since 1 April 2026, primary-sector users can claim a diesel refund on all eligible diesel use, up from 80%, provided their logbooks are kept.
Companies must also keep their registration with the Companies and Intellectual Property Commission current, or risk being deregistered, and employers must meet labour, unemployment insurance, PAYE and injury-compensation obligations. Lenders often look at the owner's personal credit history as well as the farm's. "Pay your creditors on time, keep your credit record in good standing, and make sure that every transaction on the farm is recorded," Letsitsa said.
The guide was written by Patricia Tembo for Food for Mzansi. Farmers are advised to confirm their own circumstances with SARS or a registered tax practitioner.
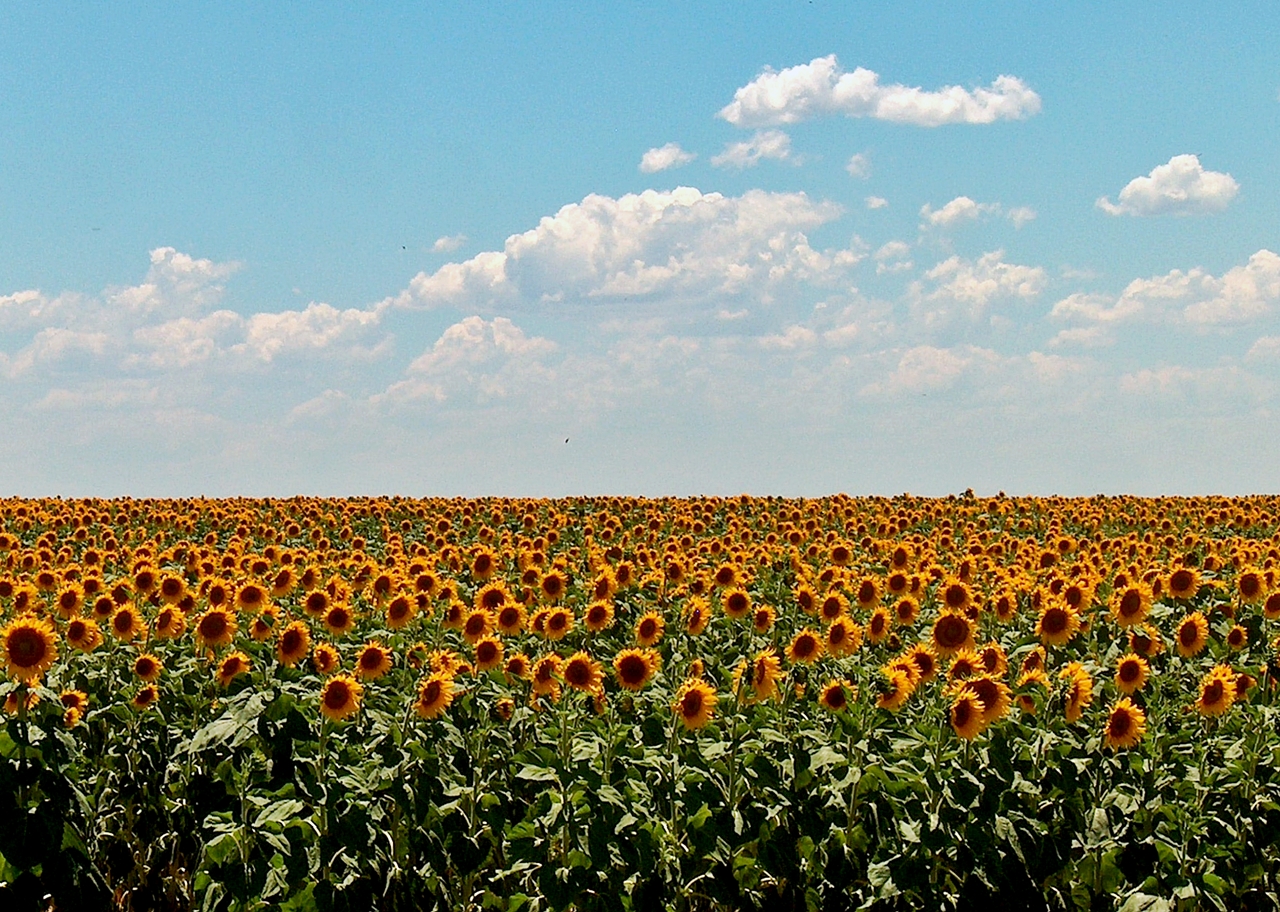
Photo: Ossewa (sunflowers near Heilbron, South Africa) / Wikimedia Commons (CC BY-SA 3.0)
Source: Food for Mzansi
Comments
(0)